
Alternative Data for Lending
Approve More Thin-file Applicants With Confidence
Thin credit files don’t tell the whole story. Use SEON’s alternative data to enrich your own credit models and verify thin-file applicants with real-time digital, device, phone and network signals.
How SEON Helps Lenders Verify Thin-File Applicants
Add real-time digital footprint, device, phone and network signals to your credit models to validate thin-file applicants and uncover hidden risk.
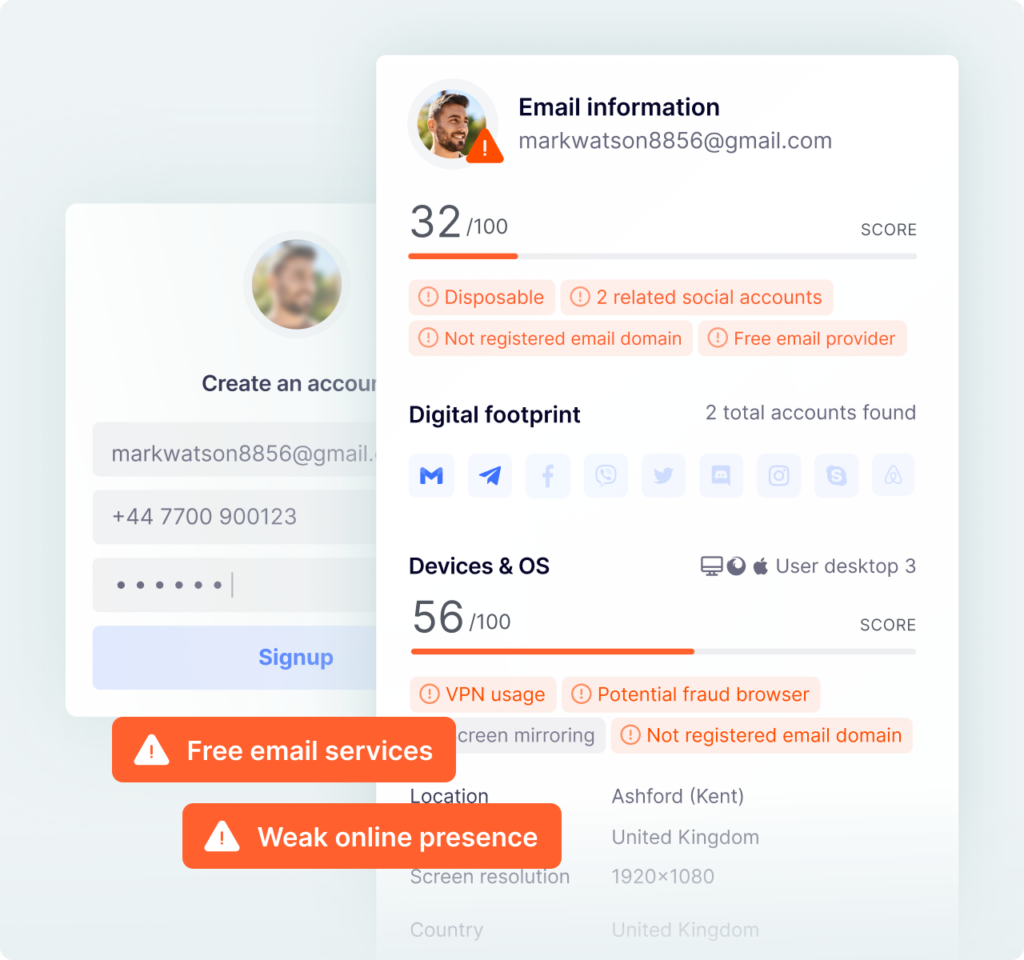
Traditional Credit Files Leave Applicants Unscored
Verify Thin-File Applicants Before You Approve
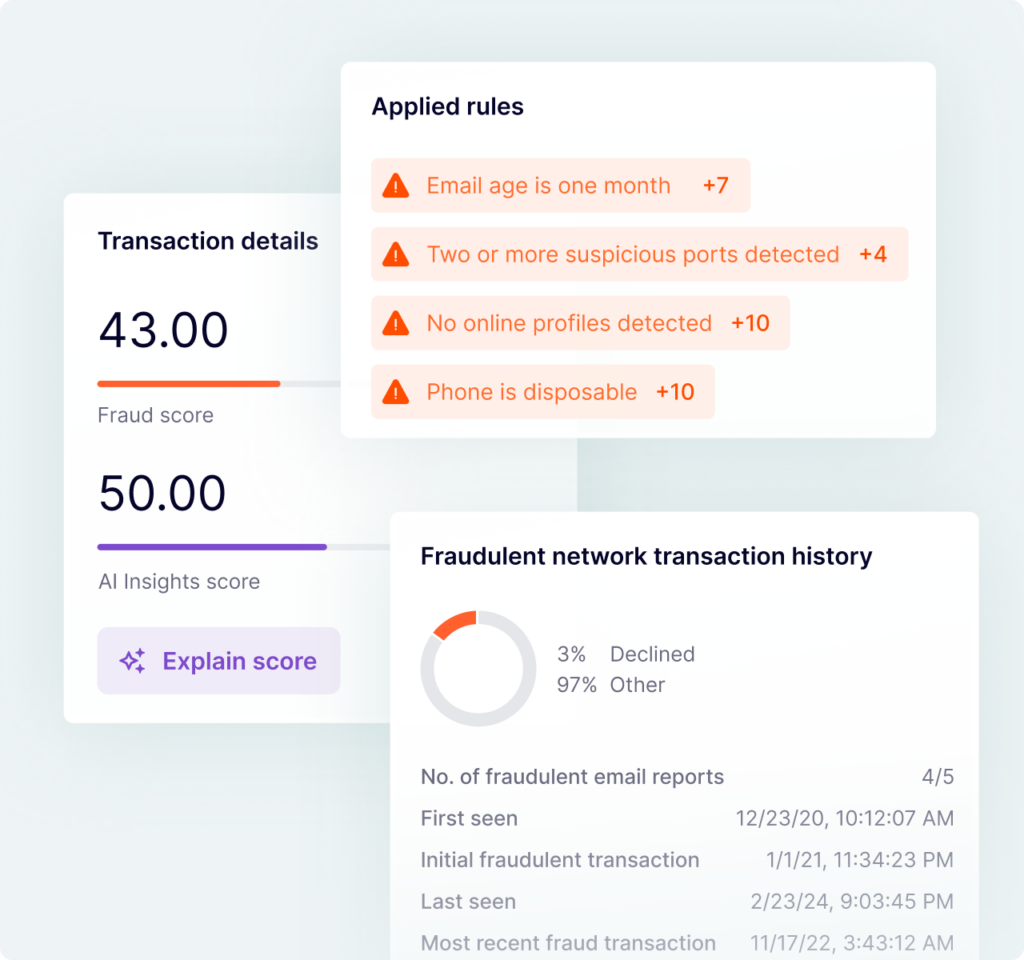
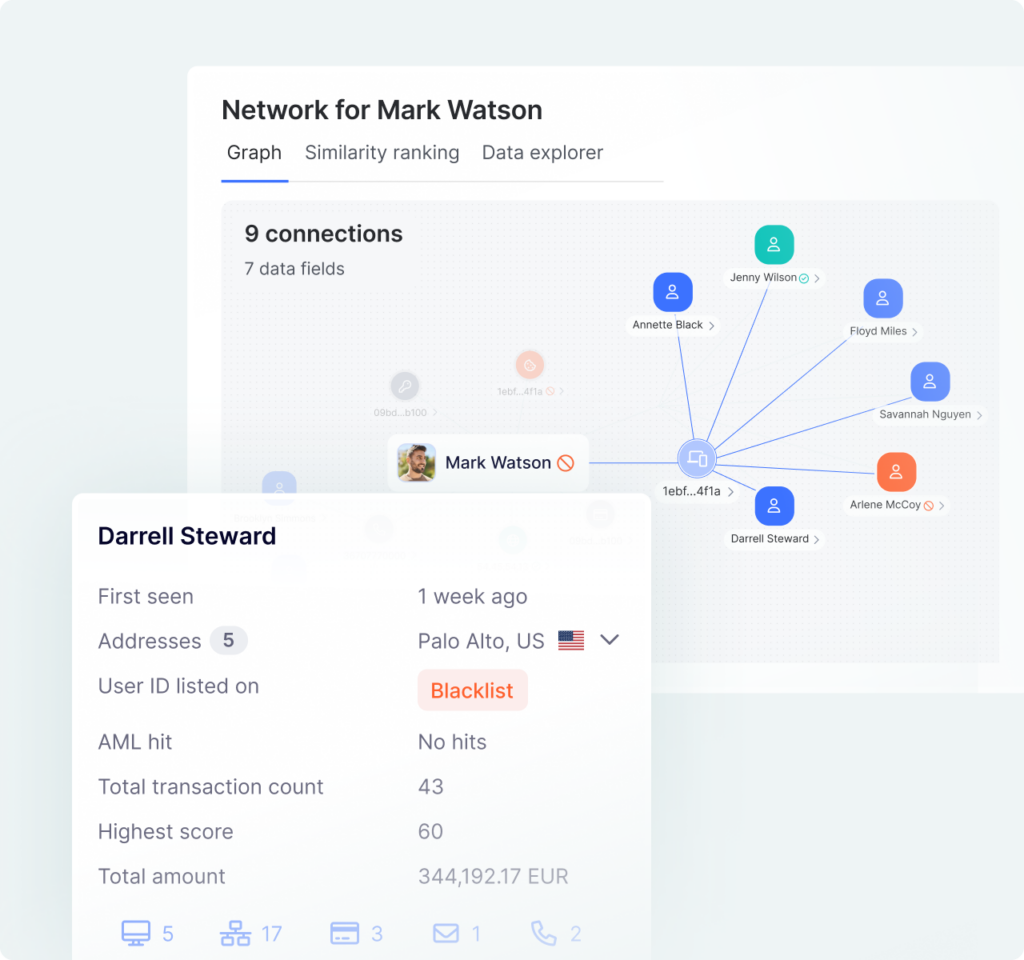
Give Your Credit Models Data They Can’t Get From a Bureau
Discover How Lenders Use SEON

“We can instantly filter out obvious fraudsters/bad debtors with no digital or social presence, and we get better intelligence to automate our decision-making.”

Juris Rieksts-Riekstins
Head of Risk at FairMoney

“Other key variables, especially those associated with email registration and phone history dates, serve as credit predictors as well.”
Lucrecia Vera
Partner, Solventa


Choose How to Integrate with SEON
The choice is up to you: integrate directly with SEON’s APIs or through the AWS Marketplace.
Learn More About Alternative Credit Scoring
-
In a world where over 1.4 billion adults remain unbanked and 7.1 million households in the United States lack access…
-
Social media credit scoring is a great solution where financial data is limited.
-
Alternative credit scoring uses digital footprints and non-traditional data to improve credit access and risk assessment.
-
Learn how to detect and prevent synthetic identity fraud with tools like digital footprinting, device intelligence, and machine learning.
The #1 AI Platform for Fraud Prevention & AML Compliance
With over 380 reviews, SEON is the market leader and G2’s best fraud prevention platform.
Frequently Asked Questions
What alternative data does SEON provide?
SEON provides real-time signals across digital footprint, device, phone, network, address and behavioral intelligence. These signals can provide additional context about an applicant’s identity and digital activity that isn’t available in a traditional credit file.
Does SEON provide a credit score?
SEON provides alternative data and risk signals that can be used within your own credit scoring and underwriting models. Lenders can decide which signals to use and how they influence their own credit decisions.
Can SEON help verify thin-file applicants?
Yes. SEON can help lenders assess whether an applicant has a genuine digital identity and consistent signals across devices, phones, networks and digital footprints. This can provide additional context when deciding whether to approve a thin-file applicant.
Does SEON replace credit bureau data?
No. SEON complements traditional credit data by adding alternative signals to the underwriting process. Lenders can combine SEON’s data with bureau information and their own credit models.
Take the First Step Toward Better Risk Decisions
“We now use the returned data [from SEON’s social media profiling] both to confirm identities, and as a debt collection tool to contact non-paying customers.”
Kaspars Magaznieks, Head of fraud, Sun Finance
Trusted by 5,000+ global organizations:


Book Time With Our Experts
This form may not be visible due to adblockers, or JavaScript not being enabled.