Virtual credit card fraud is the unauthorized misuse of digital payment credentials to execute fraudulent card-not-present (CNP) transactions. The primary risk concentrates on account takeover and automated BIN attacks, where bad actors bypass traditional card checks without physical card access.
As global virtual card volumes approach $9.1 trillion, stopping these attacks requires risk teams to detect digital anomalies before transaction authorization.
Key Takeaways
What Is Virtual Credit Card Fraud?
Virtual credit card fraud occurs when bad actors exploit digital card numbers or online onboarding vulnerabilities to conduct unauthorized purchases and steal funds.
Unlike traditional card fraud involving lost or stolen physical cards, virtual card fraud operates entirely within the CNP ecosystem. Fraudsters manipulate payment gateways through bot attacks or synthetic identity creation to generate and misuse virtual numbers.
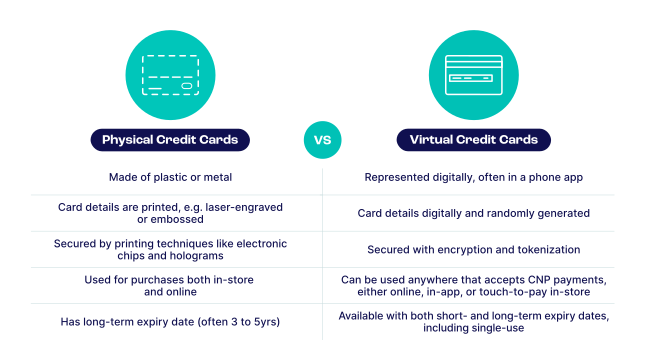
Physical vs. Virtual Credit Card Fraud
How Fraudsters Exploit Virtual Credit Cards
Virtual credit cards solve physical security gaps but introduce digital vulnerabilities that organized fraud rings actively target. Virtual credit card fraud extends beyond consumer e-commerce, leaving B2B portals and loan platforms facing equal exposure.
Without real-time BIN enrichment, risk managers must rely on extensive manual lookups to distinguish foreign virtual credit cards from high-risk prepaid cards. This gap allows bad actors to exploit low-friction onboarding processes across four primary vectors:
1. Account Takeover and Business Email Compromise
Fraudsters use leaked credentials or Business Email Compromise (BEC) to hijack user accounts. Once inside an expense portal, they generate temporary virtual cards or view existing card numbers. Standard multi-factor authentication (MFA) codes sent via email fail to block the attack because the fraudster controls the compromised inbox.
2. BIN Attacks and Automated Brute-Forcing
Using automated scripts, fraudsters take a known Bank Identification Number (BIN) and brute-force the remaining digits across payment gateways until a valid virtual card combination authorizes.
You can try SEON’s BIN Lookup tool here.
3. Cross-Account Card Recycling
On platforms handling recurring payments, such as real estate portals or buy now, pay later (BNPL) apps, fraudsters recycle the same stolen credit card hash across multiple unrelated user profiles. Without cross-account network tracking, legacy systems fail to catch these linked accounts.
4. Subscription Abuse and Trial Exploitation
Because virtual card providers allow users to generate single-use cards, bad actors create temporary cards to repeatedly exploit free trials and promotional discounts.
Fraud Vectors Across Key Industries
- Property management and rent portals. Tenants or bad actors use stolen card or bank hashes across different properties or hijack property bank accounts through unauthorized micro-deposits.
- B2B corporate cards. Employees or compromised corporate accounts exhaust spend limits on non-compliant merchant categories before risk teams spot the anomaly.
- BNPL and neobanks. Synthetic identities pass soft credit checks, obtain virtual cards and max out approval limits within minutes.
- Disbursements and prepaid cards. Physical skimming at ATMs or retail stores yields credentials that fraudsters monetize through virtual card transactions on online gateways.
How to Prevent Virtual Credit Card Fraud
Combating virtual credit card fraud requires balancing risk mitigation with low checkout friction. Implementing dynamic friction ensures legitimate buyers pass through instantly while high-risk transactions require step-up authentication.
Screen Pre-KYC Signals to Lower Verification Costs
Before triggering expensive third-party identity verification (IDV) checks, enrich basic user inputs such as email and phone data. Checking open-source intelligence (OSINT) for registered social media profiles flags disposable details or brand-new identities created for fraud.
Analyze BIN Attributes to Spot Mismatches
Analyze incoming Bank Identification Numbers in real time to establish card attributes. Differentiate between virtual cards and traditional credit or debit cards while flagging geographic mismatches between the issuing bank and the user’s IP location.
Fingerprint Devices to Catch Emulators and App Clones
Catch account takeovers and automated attacks by inspecting user hardware and browser setups. Fraud rings operating device emulators often exhibit obvious anomalies, such as screen resolutions set to 0x0 or battery levels reporting 0%.
Track Cross-Account Velocity Across Card and Bank Hashes
Monitor data velocity across card hashes and IP addresses. If the same hashed card number appears across multiple user accounts within 10 minutes, trigger an immediate block.
How SEON Helps Fight Virtual Credit Card Fraud
SEON provides a real-time decisioning engine built to detect virtual credit card fraud before transactions complete.
- Real-time BIN and card hash enrichment. Instantly classify card types and track card hashes across your platform to detect cross-account recycling.
- Pre-KYC intelligence. Filter out bad actors using email and phone social footprint checks before paying for manual checks or identity verification.
- Advanced device fingerprinting. Identify device emulators, app clones and location mismatches during registration and login.
- Customizable velocity engine. Combine Whitebox machine learning suggestions with custom rules to flag anomalous purchasing speeds or merchant category spikes.
FAQ
Can a virtual credit card be defrauded?
Yes. While virtual credit cards cannot be physically stolen, fraudsters target them through phishing, account takeover, credential stuffing and automated BIN brute-forcing attacks.
How do fraudsters get virtual credit card numbers?
Fraudsters obtain virtual card details by compromising user accounts via Business Email Compromise, intercepting credentials through phishing or using automated scripts to brute-force valid card combinations.
What is the difference between a virtual credit card and a physical card for fraud risk?
Physical card fraud relies on stolen plastic or physical skimmers. Virtual credit card fraud occurs entirely online, making device fingerprinting, IP verification and behavioral velocity tracking essential for detection.