Know Your Transaction (KYT) is the anti-money laundering practice of logging, analyzing and reporting the transactions that flow through a business, so suspicious activity is caught in the payment itself rather than only in the customer profile.
The term now carries two distinct meanings that risk teams routinely confuse: on-chain KYT, meaning blockchain and wallet analytics for crypto, and transaction monitoring on payments for banks, fintechs and payment firms.
This guide separates the two, explains how each works, and shows where behavioral and device data strengthen both.
Key Takeaways of kyt (know your transaction)
What Is Know Your Transaction (KYT)?
KYT is an anti-money laundering (AML) and counter-terrorist financing (CTF) requirement under which organizations such as financial institutions log, analyze and report their transactions. The goal is to detect fraudulent transactions and flag behavior tied to money laundering and other financial crime, terrorist financing included.
Where KYC assesses the individual at onboarding, KYT watches what that individual then does. A customer can pass identity checks cleanly and still move money in ways that signal structuring, mule activity or sanctions evasion, so the two disciplines answer different questions and run at different points in the lifecycle.
The general process runs in four stages:
- Data gathering: collating the transactions in scope.
- Data analysis: inspecting those transactions for suspicious activity, usually through transaction monitoring software.
- Risk assessment: scoring how suspicious a transaction is.
- Reporting: relaying the post-assessment findings to the relevant AML/CTF authority.
Because it leans so heavily on monitoring software, KYT is a technological, data-driven and resource-intensive operation. Staying compliant, and avoiding fines, means reviewing the program regularly for gaps and investing in real-time monitoring, which automates much of the workload and can improve return on investment (ROI) as a byproduct.
The Two Meanings of KYT: Crypto vs Payments
A common source of confusion in the market is that “KYT” describes two different jobs, and buyers often use the phrase for one while a vendor hears the other.
In crypto, KYT means blockchain analytics. It answers questions the ledger itself can reveal: has this wallet interacted with a sanctioned address, a darknet market or a no-KYC exchange, and how many hops away is that exposure? Practitioners commonly trace up to 10 hops and apply a percentage threshold, so a transaction with direct exposure to sanctioned funds is treated very differently from one where the tainted portion is small and several hops removed. This is the territory of specialist blockchain-analytics providers, and it is what crypto brokerages, stablecoin issuers and virtual asset service providers usually mean when they say they “need KYT.”
More broadly, outside crypto, people use KYT to mean transaction monitoring for AML. Here the transaction data is thinner because there is no public ledger, so the work centers on velocity rules, data-match and data-compare rules, sanctions and politically exposed person (PEP) screening on counterparties, and behavioral patterns such as an incoming transfer followed by an immediate outgoing one.
The practical takeaway: decide which KYT you actually need before you shortlist tools. Blockchain analytics and payment transaction monitoring solve different problems, and a wallet-screening product will not monitor a SEPA transfer any more than a payment-monitoring engine will trace a Bitcoin hop. The strongest setups combine both, feeding on-chain risk from a chain-analytics tool into a monitoring platform that also carries device, IP and identity signals.
Why Is KYT Important?
KYT reduces an organization’s exposure to AML compliance fines, and with it the reputational damage, resource drain and legal risk that follow being complicit in laundering or terrorist financing. As a regulatory requirement, it is part of due diligence: organizations that cannot demonstrate it face penalties and financial loss.
Its value is not only defensive. Because KYT focuses on income and outgoings, and because it is itself a risk-scoring process, a well-run program often surfaces ways to improve ROI while it runs. Transactions linked to terrorist financing can be escalated from conventional to advanced AML due diligence, where associated parties face further checks or a comprehensive manual review by risk teams, calibrated to each organization’s risk tolerance.
What KYT Means for AML Compliance
KYT sits at the core of both AML and CTF compliance because scrutinizing financial activity is a primary way to prevent laundering and terrorist financing. It delivers this through transaction and behavior monitoring, risk assessment and alert generation.
- Transaction and behavior monitoring: as a real-time process, KYT lets monitoring software flag suspiciously large transactions that occur within a dubiously short timeframe, feeding those flags into AML/CTF reporting.
- Risk assessment: data sources such as PEP lists, high-risk jurisdiction lists and negative-media and sanctions lists sharpen risk-scoring accuracy, which strengthens compliance with AML and CTF regulations.
- Alert generation: many periodic monitoring approaches do not run around the clock, whereas KYT encourages real-time analysis. A Financial Action Task Force (FATF) report on new technologies stresses that real-time threat monitoring improves communication, accountability and auditability in the data-sharing between organizations and their compliance authorities.
- Compliance with due diligence: AML rules require both customer due diligence (CDD) and enhanced due diligence (EDD), scaled to the suspicion attached to each customer. The more a business knows about its transactions, the better informed both processes become.
KYT also demands ongoing training and research on AML/CTF topics and their regulations, and that continuous employee engagement is itself a way the discipline keeps organizations compliant.
How KYT Works
KYT works by combining technology and people to record, analyze and, when suspicion arises, report transactions. The specific actions are industry-, jurisdiction- and organization-specific, and the process is becoming steadily more technological as monitoring software, risk assessment and behavioral analysis tools improve its efficiency. Even so, whether an organization runs on a periodic or real-time basis, humans still oversee much of it, particularly to keep false positives down.
The process, end to end, looks like this:
- Gather and analyze transactional data to determine a risk score. Establish the sums involved, the purpose and the parties, then use analytics to score the risk.
- Continue to monitor and act on any alerts. Alerts fire against the organization’s risk criteria and appetite. Financial institutions can, for example, run blacklist checks on the paying parties at this initial stage.
- Approve legitimate transactions and escalate suspicious ones. Innocent transactions proceed; suspicious ones are flagged for review.
- Investigate flagged transactions and notify the authority when required. Determine each transaction’s origin, purpose and parties, including any links to organized crime. Reject those that still look illegitimate and file them in a suspicious activity report (SAR) for the relevant financial authority.
Follow these steps and an organization satisfies its AML/CTF obligations while running a defensible KYT process.
Benefits of KYT
Beyond compliance and risk management, KYT makes an organization more data-driven, more secure and better equipped to support audits and even law enforcement.
- It assists law enforcement, since routine transaction analysis strengthens the evidence trail around organized crime.
- It is data-driven, giving the business a structured record of and insight into its financial activity.
- It is largely automated, because the software records and processes transactions with little manual input, which reduces the load on staff.
- It sharpens risk scoring, gauging the suspicion in each transaction and, because KYT and KYC work hand in hand, helping assess the customers behind those transactions.
- It improves ROI by flagging suspicious activity and individuals so teams can act.
- It is both deterrent and weapon against criminals, with counter-terrorist financing squarely in scope alongside anti-money laundering.
Challenges of KYT
KYT introduces friction and carries the risk of both false positives and false negatives, and because it processes, stores and transfers sensitive information, it also raises the bar on data protection.
- Customer insult rates. The friction KYT demands can reject legitimate customers on a false positive, which damages the relationship.
- False confidence. A false negative can leave an organization trusting a customer it should not, giving criminals room to operate.
- The data-protection balance. KYT is highly data-driven, so organizations must reconcile necessary data safeguards with the friction that enhanced due diligence creates when it is triggered.
None of this changes the conclusion: KYT remains one of the most effective methods of combating money laundering and other financial crime, friction and imperfect checks included.
KYT vs KYC
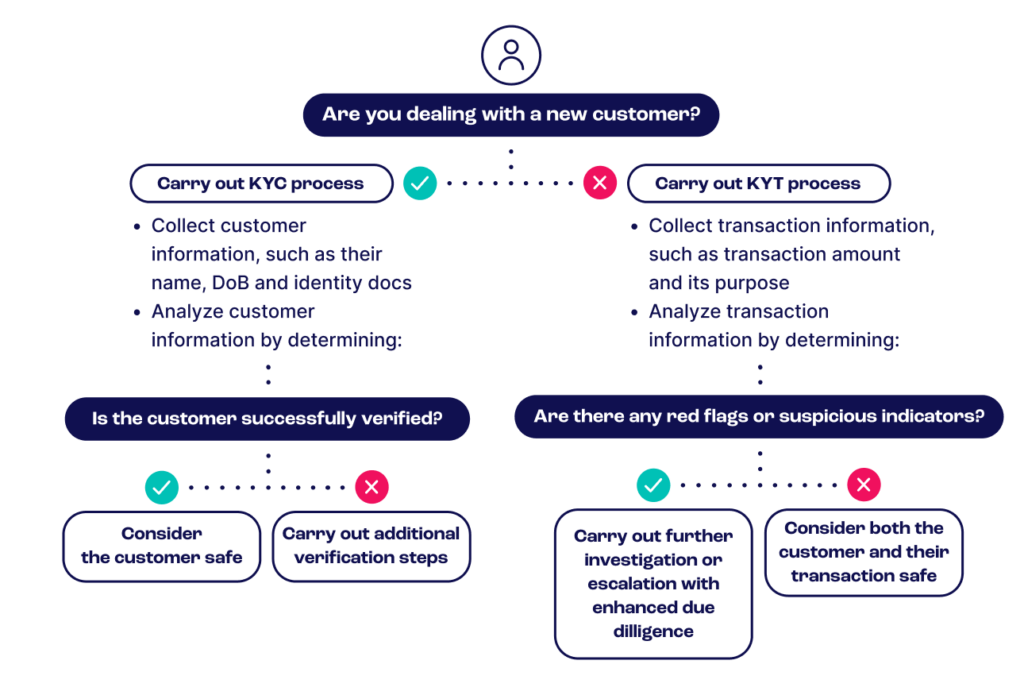
Know Your Transaction and Know Your Customer answer different questions. KYT identifies suspicious financial activity; KYC identifies suspicious individuals and behaviors. Both are mandatory AML and CTF processes, and both are becoming more automated and data-driven.
KYC runs first, at onboarding, with friction scaled to how high- or low-risk the individual appears. KYT runs afterward, on an already-onboarded customer, where whether a transaction succeeds depends on both the individual and the nature of the transaction itself.
Putting KYT into Practice
KYT earns its value at the point where onboarding ends. A customer can clear identity checks and still turn risky once money starts moving, so the transaction stage needs controls of its own rather than inheriting a clean verdict from KYC.
Some legitimate customers pass initial risk assessment despite being flagged as higher-risk, often because they appear on PEP lists or in negative media. Those accounts are prime targets for account takeover (ATO), so even when the customer is genuine, the activity on the account still has to clear the KYT stage on its own merits.
Practical KYT controls tend to combine geographic, behavioral and velocity rules. Common examples include flagging transactions made from high-risk locations, and rejecting a transaction worth 200% more than a customer’s typical payment. Layering IP geolocation and device signals on top helps separate a customer’s normal behavior from a hijacked session.
Screening backs up the monitoring. Checking parties and counterparties against PEP lists, sanctions and watchlists, refreshed in real time, catches the risk that transaction patterns alone would miss and keeps the program aligned with AML and CTF obligations.
FAQ
What is KYT (Know Your Transaction)?
KYT is the AML and CTF practice of logging, analyzing and reporting transactions to detect money laundering, terrorist financing and other financial crime in the payment itself, rather than only in the customer’s identity.
What is the difference between KYT and KYC?
KYC verifies who a customer is at onboarding; KYT monitors what that customer does afterward. KYC targets suspicious individuals, KYT targets suspicious transactions, and most programs run both.
Is KYT the same as transaction monitoring?
It depends which KYT you mean. In AML and payments, “KYT” and “transaction monitoring” are used to mean the same thing. In crypto, KYT means something different: blockchain analytics, such as wallet screening and sanctioned-address tracing. The terms line up in the payments world but diverge in crypto.
What does KYT mean in crypto?
In crypto, KYT refers to on-chain analysis of wallets and transactions, checking exposure to sanctioned addresses, darknet markets or no-KYC exchanges and tracing funds across hops.