AML transaction monitoring is the ongoing review of customer transactions to detect money laundering, terrorist financing and other financial crime, both in real time and after the fact. For most compliance teams the hard part is no longer spotting a single suspicious payment. It is doing so across fragmented tools, at scale, without burying analysts in false positives.
This guide explains what transaction monitoring is, how the process works and where programs tend to break, so you can build monitoring that holds up as your business grows.
quick summary
What Is AML Transaction Monitoring?
AML transaction monitoring is the ongoing process of reviewing customer transactions to detect suspicious or high-risk activity. It plays a central role in anti-money laundering programs by helping institutions identify potential money laundering, terrorist financing or fraud.
Analysts use transaction monitoring rules to decide when a transaction looks suspicious. These may involve:
- Unusually large or frequent transfers
- Deposits into personal or non-personal accounts
- Withdrawals or payments inconsistent with customer history
Modern systems have made this process faster and more accurate. Automation and machine learning help identify suspicious behavior in real time, reducing false positives and supporting compliance across all transaction types.
How Does the AML Transaction Monitoring Process Work?
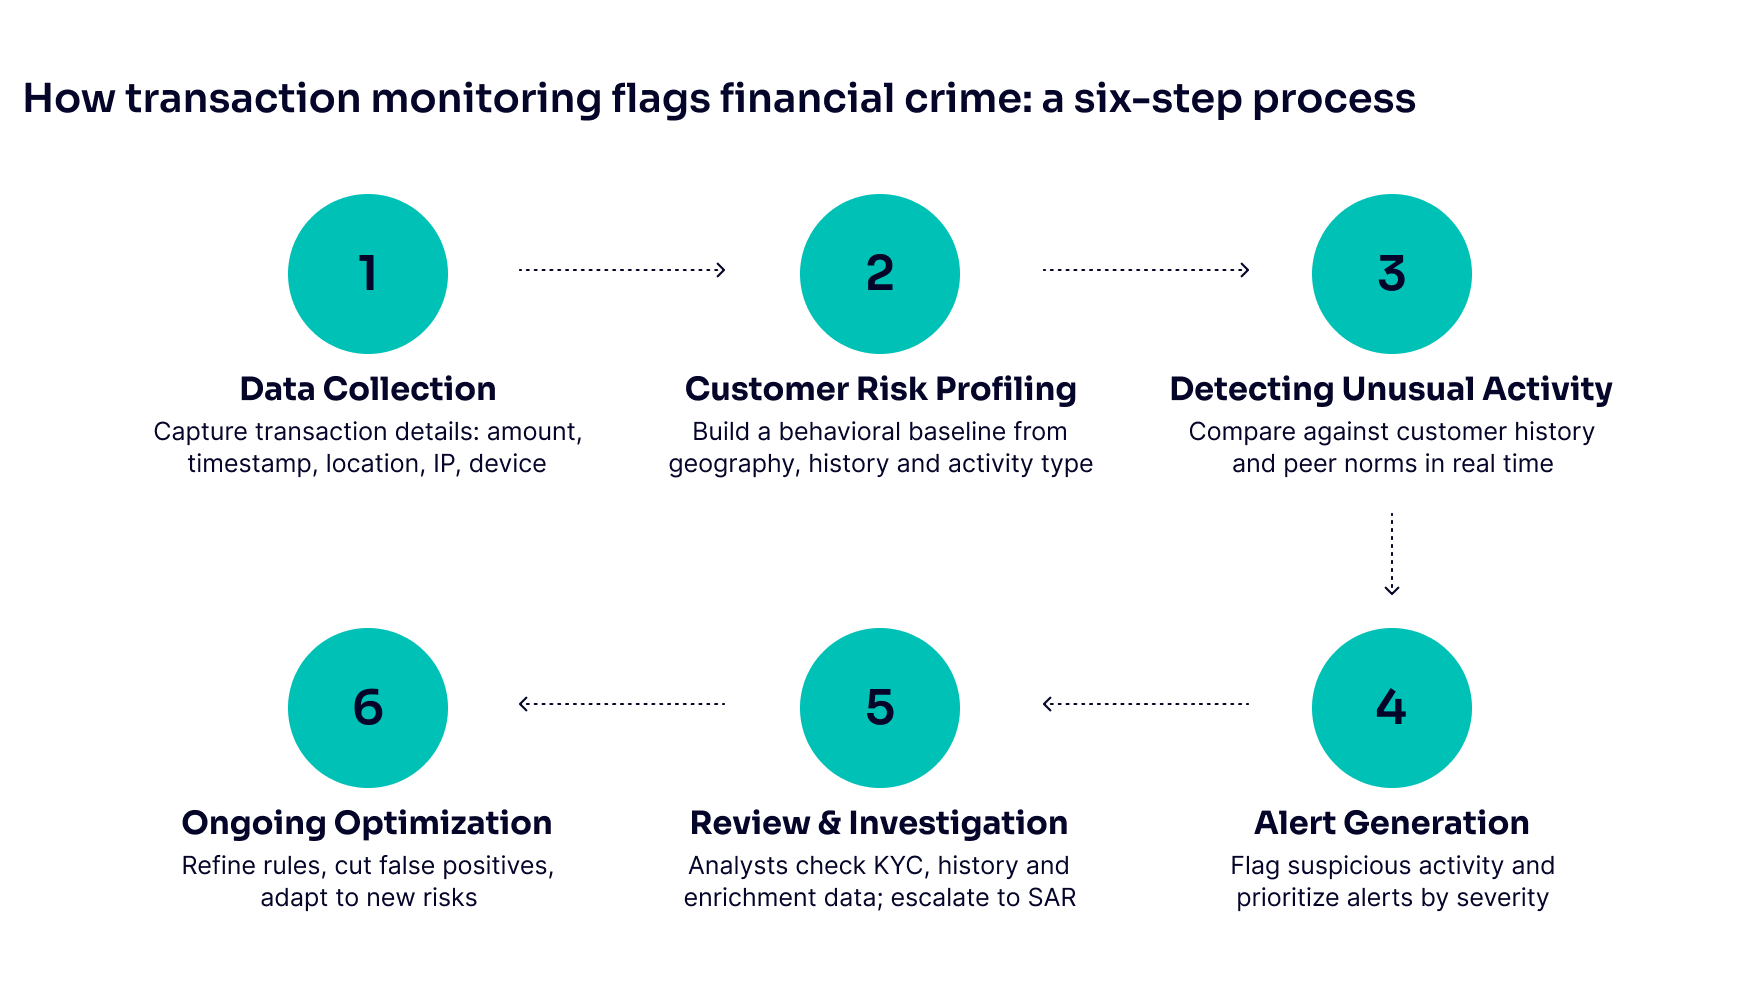
The process works by continuously reviewing customer transactions to spot activity that falls outside expected behavior. Instead of relying on one-off checks, institutions use ongoing monitoring to catch potential money laundering or financial crime as it happens.
It does this by collecting transaction data, comparing it with each customer risk profile and flagging unusual patterns for further review or investigation.
1. Data collection
The process starts with gathering detailed information about each transaction, including amounts, timestamps, locations, IP addresses, and device types. This comprehensive data forms the foundation for spotting unusual patterns and training monitoring systems to detect suspicious activity more effectively.
2. Customer risk profiling
Next, institutions build risk profiles for each customer by looking at multiple factors, such as:
- Geography: where the customer lives or transacts from
- Transaction history: typical amounts, frequency, and patterns
- Type of activity: the nature of payments, transfers, or services used
Establishing this behavioral baseline makes it easier to spot unusual activity later, for example, a sudden spike in transfers abroad or a shift to high-risk payment methods.
Customer segmentation is critical here. A transaction that looks normal for a corporate treasury account may be highly anomalous for a retail savings customer.
3. Detecting unusual activity
Transactions are analyzed in real time and compared against both the customer past behavior and peer group norms. Monitoring systems flag red flags such as sudden spikes in volume, frequent transfers to high-risk jurisdictions or attempts to stay just below reporting thresholds.
“Suspicious activity isn’t always easy to spot as it’s frequently embedded in patterns that appear mundane on the surface. However, when seen through the right lens, these signals become clear indicators of deeper risks.”
Nauman Abuzar, VP of AML Compliance and Risk
Common examples include structuring, which breaks a large transaction into smaller amounts to stay under reporting thresholds, and sudden transfers to jurisdictions with weak AML oversight. For the full list of patterns analysts watch for, see our guide to identifying suspicious financial activity.
4. Alert generation
The system generates alerts whenever it detects unusual activity. Alerts are then prioritized by severity so compliance teams can focus on higher-risk cases without being overwhelmed by low-priority reviews.
Effective alert triage separates genuine suspicious activity from false positives. Many legacy systems struggle here because overly broad rules generate large volumes of low-quality alerts.
5. Review and investigation
Analysts review flagged transactions by examining customer KYC details, historical activity patterns and enrichment data such as device intelligence or digital footprint signals. If the activity appears suspicious, the case is escalated and may lead to a Suspicious Activity Report (SAR) being filed with regulators, with every investigation step documented in a case management system to maintain the required audit trail.
6. Ongoing optimization
Effective AML transaction monitoring must evolve alongside new risks, so institutions regularly refine detection rules, adjust monitoring strategies and reduce false positives to keep systems accurate over time. Modern platforms can also accelerate regulatory reporting by assisting with SAR narrative generation and automating parts of the reporting workflow.
Why Is Transaction Monitoring Important?
Transaction monitoring is essential because it ensures regulatory compliance, enables proactive risk detection and strengthens customer due diligence. Effective monitoring helps institutions uncover financial crime red flags early, protect customers and maintain trust by continuously assessing behavior and updating risk profiles in real time.
The stakes are only growing: the global transaction monitoring market is projected to reach $9.38 billion by 2030, according to MarketsandMarkets, as institutions face increasing pressure to detect financial crime at scale.
Why Is it essential for regulatory compliance?
Global frameworks such as FATF, the EU’s 6AMLD and U.S. FinCEN guidelines require institutions to detect and report suspicious activity tied to money laundering and terrorist financing. Failure to meet these obligations can result in heavy fines, remediation orders, license loss and significant reputational damage, as seen in major enforcement cases like Westpac’s AUD 1.3 billion penalty for inadequate monitoring.
Common Challenges in AML Transaction Monitoring
Transaction monitoring carries several recurring AML compliance challenges: high false-positive rates, fast-evolving fraud tactics, fragmented tooling and a heavy regulatory reporting burden. The specific red flags differ by industry, so effective monitoring has to account for the risks unique to each sector.
Risk indicators by industry
- Banking, financial services and fintech. High volumes of digital and cross-border activity raise exposure to layering, synthetic identity fraud and fraudulent account openings. Common indicators: sudden spikes in international wire transfers, transactions just below reporting thresholds, dormant accounts turning active, rapid fund movement across multiple accounts and repeated failed authentication attempts.
- Payments, PSPs and marketplaces. The main risks are fraudulent chargebacks, fake merchant accounts and laundering through refund schemes. Watch for mismatched billing and shipping details, many transactions from one device or IP across different payment methods and unusually high-value orders from new accounts.
- Crypto and virtual assets. Pseudonymity and decentralized rails drive exposure to illicit flows. Red flags include transfers to or from unhosted wallets, newly created wallets moving large sums, exposure to high-risk jurisdictions and rapid on-ramp then off-ramp used to obscure the source of funds.
- iGaming and online gambling. The sector faces money laundering, fraud and bonus abuse. Suspicious signs: deposits followed by minimal gameplay and fast withdrawal, multiple accounts tied to one device, wagers inconsistent with the player profile and shifting payment methods across linked accounts. Operators must satisfy both gambling-license and AML/CTF reporting duties, which overlap but differ.
- Lending and BNPL. As products move toward repeat customers, risk shifts to first-party and synthetic identity fraud at application, early repayment or over-payment against stated income and structuring around CTR and Form 8300 thresholds.
- Trading and investment platforms. Rapid buying and selling can be used to obscure fund origin. Indicators include high trading volume with little economic rationale, frequent deposits and withdrawals without meaningful trading and coordinated activity across linked accounts.
The common thread: Fragmentation
Across every sector the underlying failure is rarely detection logic. It is fragmentation. When screening, monitoring, case management and reporting sit in separate tools, analysts move data by hand, rigid siloed rules flood them with low-quality alerts, and SAR, CTR and Form 8300 filing stays manual. The backlog between an alert and a filed report is exactly what regulators scrutinize.
Consolidation is the fix: behavioral, device and transactional signals, configurable rules, machine learning and case management in one place, so teams spend time mitigating risk rather than moving data. For how these rule sets are typically structured, see our guide to advanced AML transaction monitoring rules.
What to Look for in an AML Transaction Monitoring System
Modern AML transaction monitoring requires more than static rulebooks. An effective system must adapt quickly to evolving risks, support regulatory expectations and give investigators clear visibility into suspicious behavior. The capabilities below define a scalable, compliant approach.
- Real-time detection: Screening transactions as they occur helps institutions identify unusual patterns immediately, reducing exposure and enabling faster escalation.
- Contextual behavioral analysis: Strong systems look beyond transaction amounts by incorporating behavioral, device and geolocation signals, which helps distinguish genuine customer activity from hidden typologies.
- Flexible, configurable rules: Rule logic should be adjustable without engineering involvement, so most modern platforms support no-code or low-code rule builders that let compliance teams update thresholds and logic as policy and risk appetite change.
- Prioritized, high-quality alerts: With rising volumes, systems must sort alerts by severity, customer risk and typology relevance, which reduces noise and directs investigators toward the most critical cases.
- Integrated sanctions and watchlist screening: Effective solutions screen customers and transactions against up-to-date sanctions lists, PEP data and adverse media, strengthening regulatory coverage and audit defensibility.
- Full investigation tools: A complete system supports the full path from alert to SAR filing, with role-based access so fraud and compliance teams can work the same case, plus an audit trail that documents every step for regulators.
For a closer look at how SEON puts these capabilities into practice, including agentic AI-assisted case building, see the AML transaction monitoring solution page.
Compare leading transaction monitoring software to see how each helps detect suspicious activity and maintain compliance.
Read more
Batch vs Real-Time Transaction Monitoring
Batch monitoring and real-time monitoring represent two different approaches to reviewing transactions for suspicious activity.
Batch monitoring reviews transactions after processing, typically at the end of the day or during scheduled intervals, which meets basic compliance requirements but delays the identification of potentially illicit behavior.
By contrast, real-time transaction monitoring screens transactions as they happen, enabling institutions to respond instantly before further damage occurs. Although real-time AML monitoring isn’t mandated by regulators, it is widely regarded as best practice, helping reduce risk, accelerate investigations and ensure timely SAR filings.
To explore more about how this approach compares with batch screening, see our deep dive on real-time vs batch monitoring.

Building an Effective AML Transaction Monitoring Program
Effective transaction monitoring comes down to a few principles: screen in real time, tie rules to a risk-based approach, and unify fraud and AML signals so context is not lost between teams. Programs that do this catch suspicious activity earlier and waste less time on false positives.
The operational goal is consolidation. Bringing behavioral, device and transactional data, configurable rules and case management into one workflow lets teams move from alert to decision to report without re-keying data between systems, which is what keeps a program accurate as volumes grow.
“The teams that scale cleanly are the ones that collapse fraud and AML into one view and cut the manual reporting effort. The backlog between an alert and a filed report is exactly what examiners come looking for.”
Nauman Abuzar, VP of AML Compliance and Risk
Transaction Monitoring FAQs
What AML typologies can be detected through transaction monitoring?
Transaction monitoring helps identify key AML typologies such as structuring, layering, mule activity, high-risk jurisdiction transfers and sudden account behavior changes. By analyzing transaction patterns, customer history and contextual data, institutions can detect abnormal movements that may indicate money laundering or other financial crimes.
What global regulations govern AML transaction monitoring, and what are the penalties for non-compliance?
Global AML regulations, such as the FATF Recommendations, the EU AML Directives, and the U.S. Bank Secrecy Act, require financial institutions to monitor transactions for suspicious activity. Failure to implement effective monitoring can result in significant penalties, including multimillion-dollar fines, regulatory sanctions and even criminal liability for compliance failures. Regulators like FinCEN, the European Banking Authority and the UK’s FCA actively enforce these obligations worldwide.
What are examples of suspicious activity detected by AML transaction monitoring?
AML transaction monitoring detects financial behaviors that may indicate money laundering, fraud, or terrorist financing — such as large or frequent cash deposits, transfers just below reporting thresholds, or movements involving high-risk jurisdictions. Automated transaction monitoring tools help uncover these patterns efficiently across large transaction volumes.
What role does transaction monitoring play in AML compliance?
Transaction monitoring is the primary mechanism for detecting suspicious activity on an ongoing basis. It connects the initial risk assessment performed during customer onboarding with continuous oversight throughout the customer relationship, supporting the identification and reporting of potential financial crime.
How does transaction monitoring work in banks?
Banks apply transaction monitoring across high volumes of retail and corporate activity. Retail accounts are typically monitored for structuring and unusual cash patterns, while corporate accounts are screened for anomalous cross-border transfers and trade finance flows. Banks are subject to direct regulatory examination of their monitoring programs, making consistent alert handling and documented audit trails especially important.